
Celestica will report its third-quarter 2026 results after the market closes on Monday, Oct. 26, and the number to beat is one the company wrote itself. In its July 27 results release, the Toronto-based maker of AI networking and server hardware guided Q3 revenue of US$5.25 billion to US$5.55 billion and adjusted earnings per share of US$2.88 to US$3.08. Management takes questions on a webcast at 8 a.m. ET on Tuesday, Oct. 27, which doubles as its 2026 Investor and Analyst Day, according to the company.
That midpoint, about US$5.4 billion (about CA$7.6 billion), would be roughly 69% more than the US$3.19 billion Celestica booked in the same quarter of 2025. The company reports in U.S. dollars and trades on both the NYSE and the TSX under CLS.
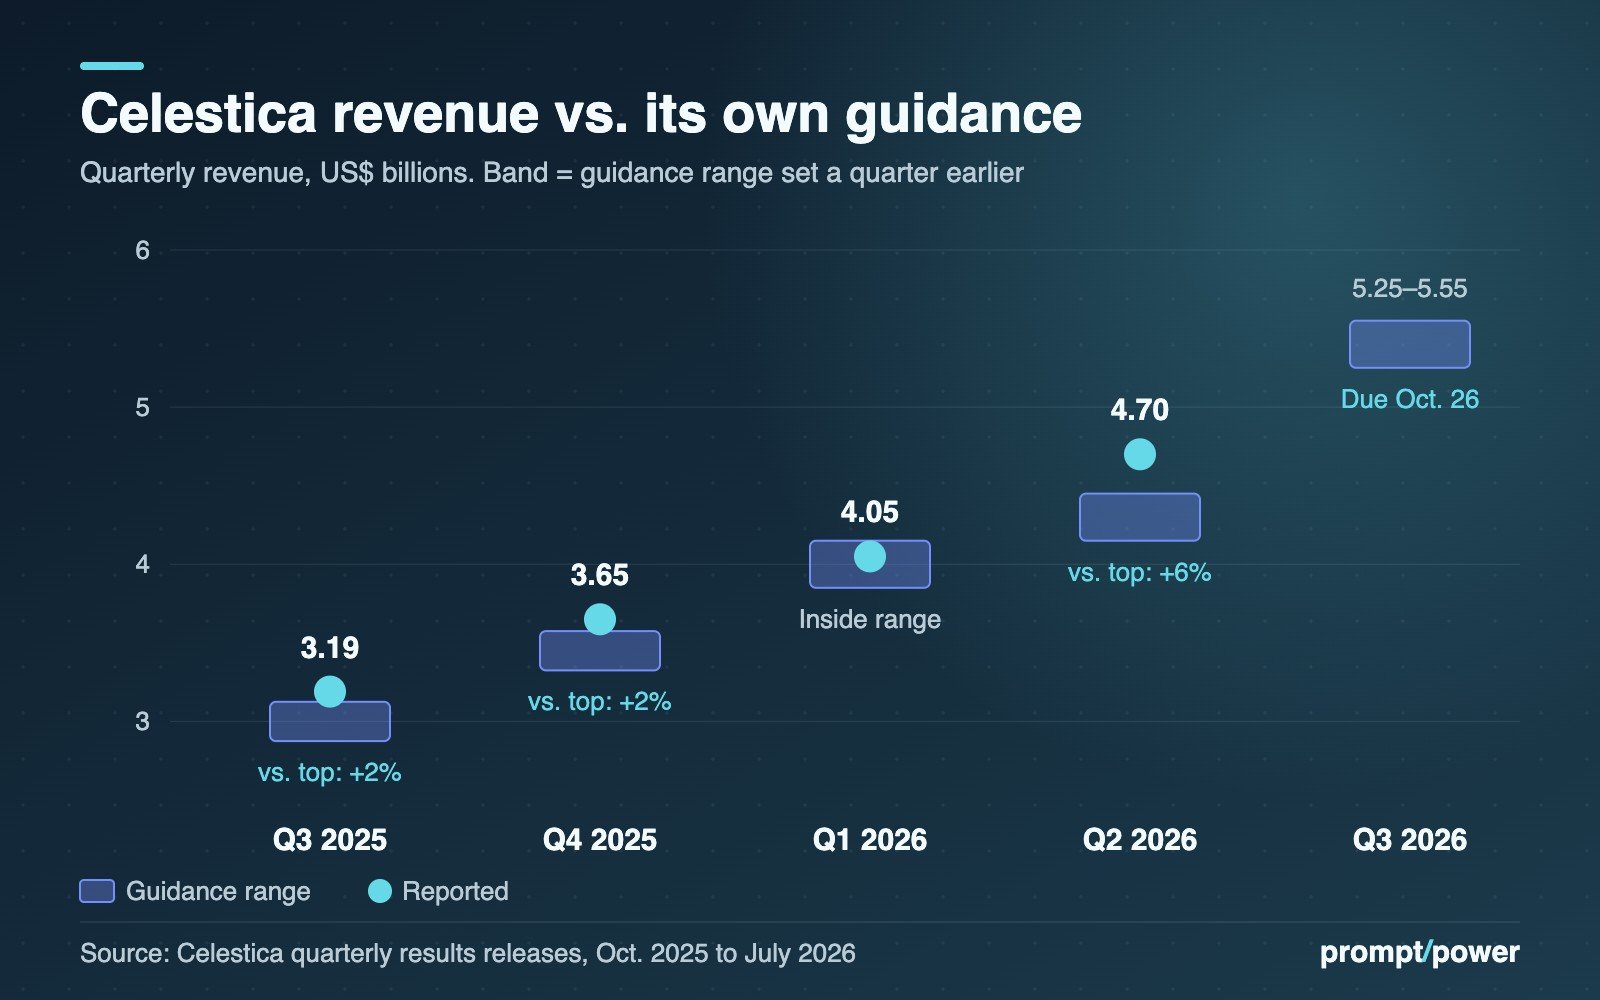
We went back through Celestica’s last four quarterly releases and lined up each quarter’s guidance range against what it delivered. The pattern is the most useful preview there is.
Celestica’s guidance record: four quarters, line by line
Every figure below comes from Celestica’s own releases, filed with the U.S. Securities and Exchange Commission. Revenue is in billions of U.S. dollars. The CCS share is our calculation: Connectivity & Cloud Solutions segment revenue divided by total revenue.
| Quarter | Revenue guidance | Actual revenue | Adj. EPS guidance | Actual adj. EPS | CCS share |
|---|---|---|---|---|---|
| Q3 2025 | 2.875–3.125 | 3.19 | 1.37–1.53 | 1.58 | 75% |
| Q4 2025 | 3.325–3.575 | 3.65 | 1.65–1.81 | 1.89 | 78% |
| Q1 2026 | 3.85–4.15 | 4.05 | 1.95–2.15 | 2.16 | 80% |
| Q2 2026 | 4.15–4.45 | 4.70 | 2.14–2.34 | 2.54 | 81% |
| Q3 2026 | 5.25–5.55 | Oct. 26 | 2.88–3.08 | Oct. 26 | ? |
Adjusted EPS cleared the top of the range in all four quarters. The margins were thin at first (five cents in Q3 2025, one cent in Q1 2026) and then wide: Q2’s US$2.54 beat the high end by 20 cents.
Revenue is where it gets interesting. Three times out of four, Celestica finished above its own ceiling. The exception was Q1 2026, when revenue of US$4.05 billion landed inside the US$3.85 billion to US$4.15 billion range, about US$100 million short of the top. The company’s April 27 release was careful about the wording, saying only that adjusted EPS was “above the high end of our guidance range.” Then Q2 came in at US$4.70 billion, US$250 million over the top of its range.
Measured against the midpoint, the beats were 6.5%, 5.9%, 1.2% and 9.3%. Our arithmetic, not the company’s: if Q3 2026 beats its midpoint by the four-quarter average of about 5.7%, revenue would come in near US$5.7 billion. A result at the top of the range, US$5.55 billion, would be the second-weakest beat of the five quarters.
Why the CCS segment is the whole story
Celestica runs two segments. Connectivity & Cloud Solutions (CCS) carries its AI data-centre hardware. Advanced Technology Solutions (ATS) is everything else.
In Q2 2026, CCS revenue rose 84% to US$3.81 billion, with a segment margin of 8.7%. ATS grew 8% to US$0.89 billion. Working back from those growth rates, CCS was about 72% of revenue a year earlier. Since Q3 2025, the CCS share of revenue has climbed every quarter, from 75% to 81%.
Celestica also breaks out Hardware Platform Solutions (HPS), its own-design hardware line. HPS revenue was about US$1.9 billion in Q2, up 58%. That growth rate has slowed each quarter, from 79% in Q3 2025 to 72, 63 and now 58%, while CCS overall has accelerated. Our read: most of the newest growth is coming from outside HPS, which makes the handful of very large buyers even more important.
Those customers are few. In its Jan. 28 release, Celestica disclosed that three customers accounted for 36%, 15% and 12% of fourth-quarter 2025 revenue. That is 63% of the company from three buyers, which it does not name in the release.
Three customers accounted for 63% of Celestica’s revenue in the fourth quarter of 2025.
The full-year 2026 outlook has been raised twice
The annual guide matters as much as the quarter. Celestica entered April with a 2026 revenue target of US$17.0 billion. On April 27 it raised that to US$19.0 billion and lifted adjusted EPS to US$10.15 from US$8.75. On July 27 it raised again, to US$20.5 billion in revenue, US$11.30 in adjusted EPS, US$600 million in free cash flow and an 8.4% adjusted operating margin. For comparison, all of 2025 brought in US$12.4 billion.
Subtract the first half (US$4.05 billion plus US$4.70 billion) from US$20.5 billion and the company needs about US$11.75 billion in the second half. With Q3 at its US$5.4 billion midpoint, that implies a fourth quarter of roughly US$6.35 billion. Watch whether Monday’s release keeps US$20.5 billion, which would quietly lift that implied Q4 if Q3 beats, or raises it a third time.
Then there’s 2027. The July release said Celestica expects revenue growth next year “to accelerate beyond the 65% anticipated for 2026,” with adjusted EPS growing faster than revenue. On our math, more than 65% growth on US$20.5 billion would mean revenue above US$33.8 billion. An investor day is the natural place to put a number on that. Last year’s, held on Oct. 28, 2025, came the morning after Q3 results, the same format Celestica is using now.
What to watch on Oct. 26 and 27
- Revenue against US$5.55 billion. A print above the ceiling keeps the streak intact. Inside the range, as in Q1, is the scenario the stock has not seen since April.
- Adjusted EPS against US$3.08. Four for four on the top end. A fifth would extend it.
- Q4 guidance. Anything near or above the implied US$6.35 billion tells you the full-year number is going up.
- CCS share. Crossing 82% would mean the AI segment is still outgrowing everything else.
- Customer concentration. The July release did not repeat the top-customer split. If Monday’s documents show the largest customer above 36%, that is the risk worth pricing.
- A 2027 figure. The company has promised acceleration. An actual target would be new.
There is a legal item in the background. Celestica is one of 20 companies named in a U.S. International Trade Commission investigation over power hardware for AI servers, which we covered on Oct. 19. Nothing is blocked while that case runs, but analysts may ask about it on the call.
How to follow Celestica’s Q3 results
The results release goes out after the close on Oct. 26 on Celestica’s investor site. The Oct. 27 call is a public webcast; Celestica says a recording will be posted about two hours after it ends. The in-person part of the investor day, a lunch forum in Midtown Manhattan with chair and chief executive Rob Mionis and his leadership team, is limited to institutional investors and sell-side analysts who register in advance.
For context on where Celestica sits in the AI hardware supply chain, see our report on Microsoft’s Maia 300 chip and the Nvidia math behind it and last week’s ASML Q3 earnings and its supply warning. New to quarterly filings? Our guide to reading an AI company’s S-1 covers the same numbers in a different document. More from the hardware desk.
In July, Mionis said the 8.2% adjusted operating margin “represents another new high for the company.” The Q3 guide assumes 8.4%. One more new high is already baked into the range Celestica has to beat.
Jeff Cameron writes about the business and policy side of AI for prompt/power. A chief operating officer by trade, he also writes for Not An Atlas.
Keep reading


Latest from prompt/power
- SK hynix Memory Is Sold Out Through 2029. PCs and Phones Pay the PriceOct 29
- GPT-6.1 Terra Price: US$1 In, US$5 Out. What Agents Cost Now, and the CatchOct 29
- Australia’s Chatbot ‘Intimacy’ Ban Is for Kids Only. Canada’s Bill Isn’tOct 29
- Cohere Caught Qwen Trying a Beijing Upload. How to Lock Down AI AgentsOct 29
- Cloudflare’s AI Leaked Other Customers’ Data in 155 Replies. What to CheckOct 29
Leave a Reply